Key Takeaways:
- Spot gold sold off after the September CPI rose 0.6 percent month-on-month (3.7 percent year-on-year) and PPI rose 1.3 percent monthly (6.3 percent annually), as traders priced in a higher probability of further Federal Reserve rate hikes, before recovering most losses to trade in the mid-$4,150s.
- The article argues that markets are reacting to expected policy responses rather than inflation itself, and that official statistics understate the erosion of household purchasing power while central banks remain constrained between inflation risks and financial fragility.
- It maintains that the structural case for gold is intact amid rising global debt, continued central-bank purchases, fiscal strains and protests across Europe, and intensifying geopolitical conflicts, viewing short-term corrections as opportunities rather than a change in thesis.
The recent reaction in the gold market to the September US inflation data offers a textbook illustration of how short-term speculative noise can obscure and distort longer-term realities. After the CPI print showed a 0.6% month-on-month rise and 3.7% year-on-year, followed by an even hotter PPI of 1.3% monthly and 6.3% annually, spot gold sold off sharply. Prices briefly tested levels near $4,070–$4,100 before recovering most of the ground. By mid-week the metal was trading again in the mid-$4,150s, still on track for a modest weekly decline but far from any structural breakdown.
On the surface, the move appears paradoxical. Higher inflation should support gold as a store of value and inflation hedge. If the currency’s purchasing power is shrinking, it should be a boost for the only form of money that is un-inflatable. Instead, traders rapidly marked up the probability of further Federal Reserve rate hikes and adjusted their positions accordingly. This is the classic short-term dynamic: the market is pricing the policy response rather than the inflation itself.
Yet this reaction is precisely what one would expect in a system that has become highly sensitive to every data point and every shift in the expected central-bank path. The market has grown so dependent on the state and its central bankers that every piece of information is weighed on that scale. A bad jobs report has the same effect. Instead of wondering what is wrong and why people are losing their jobs, the employment drop is celebrated because it means monetary support is on the way. It is taken for granted that said support will always and unfailingly show up to prop up asset prices and to protect the interests of those closest to the state, its institutions and its cronies. In this light, any and all flashing red lights coming from the real economy are read as bullish omens: to the near-sighted, bad news is good news.
Nevertheless, being myopic and naive enough to believe that this can go on forever, does not alter the underlying fundamentals. Official measures continue to understate the true erosion of purchasing power that ordinary households experience in food, energy, housing and services. Energy costs, in particular, remain elevated and are feeding through into broader prices. Central banks find themselves once again trapped: they cannot ease without risking a renewed inflationary surge, nor can they tighten aggressively without exposing the fragility of highly leveraged balance sheets and heavily indebted sovereigns. The result is where we stand today: policy paralysis dressed up as data-dependence.
Looking beyond the weekly charts, which is something everyone should do, the structural case for gold remains intact and, if anything, has strengthened considerably over the last months. Global debt levels continue to climb toward levels that are mathematically unsustainable without either prolonged financial repression or outright monetization. Trust in fiat currencies and in the institutions that manage them continues to erode as official statistics increasingly diverge from lived experience. Central banks themselves have been steady buyers of physical gold for years and continue to be, quietly diversifying away from the very system they administer and from the very currencies they print.
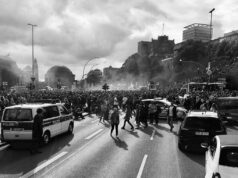
The geopolitical and political backdrop only reinforces this picture. Across Europe, public finances are under intense strain. France is a great example of what happens when you run out of money to the extent that people actually start to notice. The country faces mounting debt-service costs, student and public-sector protests, and growing market skepticism about its fiscal trajectory. The government cannot “pay off” the protesters to make the mayhem stop because it cannot afford to address their complaints about dilapidated school buildings, overcrowded classrooms and teacher shortages. Belgium is also seeing large anti-austerity demonstrations and clashes with police. The Spanish Prime Minister just last week had to call a snap election because of massive protests over the nation’s housing crisis.
Similar discontent over living costs, education, housing and budget cuts has appeared in multiple other countries. These are just symptoms of a broader exhaustion of the post-crisis policy model that combined high public spending, demographic pressures, energy vulnerability and declining productivity growth. Domestic political fragmentation and the persistent risk of wider conflict further undermine confidence in paper claims and political promises.
And that’s to say nothing of the two wars that are not just ongoing, but intensifying. When one looks at this particular big picture and realizes just how dire the straits we’re in actually are, obsessing over a quarter point interest rate cut or hike suddenly looks like a rather striking exercise in missing the forest for the trees.
In such an environment, temporary corrections driven by rate expectations or technical positioning should be viewed as opportunities rather than signals of a changed thesis. Gold does not need continuous parabolic advances to fulfill its role. The metal’s long-term value derives from its status as the only form of money that cannot be created at will by political authorities, that requires no counterparty, and that has survived every previous episode of monetary excess and institutional decay.